The reinsurance sector is witnessing a significant shift as life insurers increasingly embrace sidecar structures and offshore reinsurance platforms. This strategic move, often in collaboration with alternative investment managers, is designed to optimize capital, foster business growth, and enhance profitability. These innovative arrangements provide insurers with flexible avenues for managing their capital needs, accommodating new business volumes, and mitigating overall risk exposure. The trend is expected to gather further momentum, reflecting a growing alignment between insurance entities and the investment community.
Key players in the North American life insurance landscape are actively forming these collaborative ventures. For instance, recent developments include a substantial $1 billion capital commitment from Blackstone-managed funds to support a new flow reinsurance structure for F&G Annuities & Life, Inc. Similarly, Japan Post Insurance has committed $2 billion to a reinsurance co-investment vehicle with Global Atlantic Financial Group, an entity associated with KKR. These partnerships underscore a broader industry movement towards leveraging external capital for strategic expansion and enhanced financial resilience.
Expanding Horizons: The Rise of Sidecars in Life Reinsurance
The latest insights from Fitch Ratings indicate a sustained surge in alliances between North American insurers and alternative investment managers, predominantly through the establishment of sidecars and offshore reinsurance platforms. This strategic evolution is largely influenced by the allure of more economically viable and less capital-intensive regulatory frameworks, with Bermuda emerging as a preferred domicile due to its refined regulatory environment in 2024. These structures enable insurers to access additional capital resources, fueling both organic growth through new annuity sales and inorganic expansion via strategic acquisitions. The model allows for an improved capital position, providing the necessary foundation for ambitious market endeavors.
The increasing formation of offshore reinsurance platforms and sidecar vehicles, often under the ownership of alternative investment managers, has spurred a rise in reinsurance transactions. This trend enables the life insurance industry to divest itself of capital-intensive legacy liabilities, thereby streamlining operations and bolstering financial flexibility. While these arrangements offer significant advantages in terms of capital management and risk reduction, the sheer volume of some transactions necessitates careful consideration of growth sustainability and counterparty credit risks. Nonetheless, the prevailing outlook suggests a continued expansion of these partnerships, with minority stakes, sidecars, and offshore reinsurance platforms serving as primary mechanisms for future collaborations.
Capital Optimization Through Strategic Collaborations
The strategic deployment of sidecars and offshore reinsurance platforms by life insurers, often in partnership with alternative investment managers, represents a concerted effort to optimize capital and drive business expansion. These arrangements offer a dual benefit: providing critical capital resources for insurers to support growth initiatives, such as retail annuity sales and strategic acquisitions, while also enabling them to enhance earnings by attracting third-party capital. Bermuda's regulatory enhancements have further solidified its position as an attractive jurisdiction for these structures, offering a conducive environment for capital efficiency and oversight. The collaborative model facilitates the shedding of capital-intensive liabilities, transforming the financial landscape for participating insurers.
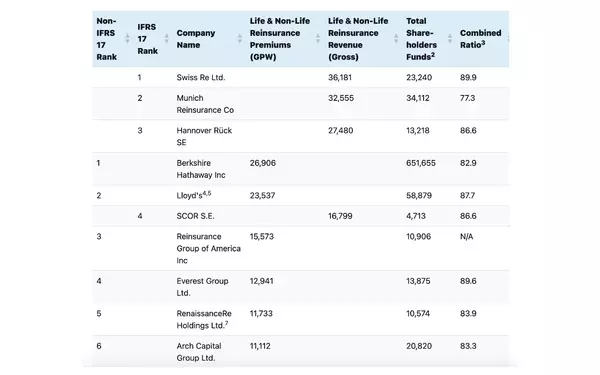
The burgeoning activity in the life and annuity sidecar sector is underscored by several high-profile deals. Beyond the significant investments by Blackstone and Japan Post Insurance, MetLife, Inc. and General Atlantic’s Chariot Reinsurance recently completed its inaugural transaction, assuming $10 billion in liabilities. Moreover, Reinsurance Group of America (RGA) has reported meaningful fee income from its Ruby Re life reinsurance sidecar, capitalized by third parties. Allianz also entered this space with Sconset Re Ltd. towards the end of last year. This momentum is not confined to life and annuity, as evidenced by Aon's prediction of new casualty reinsurance sidecars launching in 2025 and 2026, indicating a broader industry adoption of this capital-efficient structure.