The reinsurance market in Florida is experiencing a notable restructuring. Two significant state-supported reinsurance mechanisms have recently been altered, signaling a greater reliance on private sector solutions. This recalibration is poised to redirect Florida-based insurance companies towards the open market for their risk transfer requirements, reflecting a broader strategy to enhance the stability of the state's property insurance framework.
Legislative Changes Impact Florida's Reinsurance Structure
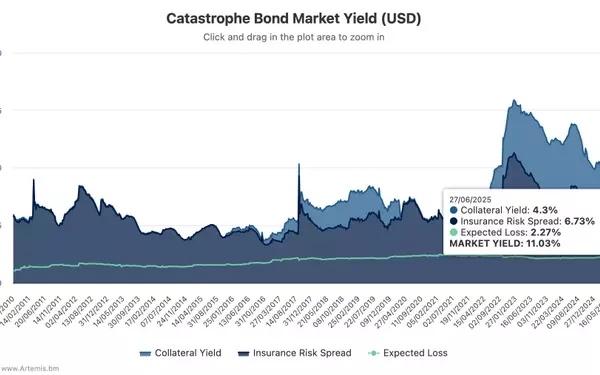
In a pivotal development, Florida's Governor, Ron DeSantis, recently enacted House Bill 5013. This legislative action has set in motion substantial modifications to the state's reinsurance infrastructure. Primarily, it mandates a significant reduction in the scope of the Reinsurance to Assist Policyholders (RAP) initiative, effectively shrinking its capacity by more than half. Concurrently, the bill entirely revokes the Florida Operational Reinsurance Assistance Program (FORA), eliminating another state-backed reinsurance source. These programs, initially designed to offer crucial support to the state's struggling insurance carriers, especially in the aftermath of severe weather events like Hurricane Ian, are now undergoing a dramatic shift. The RAP program's maximum payout has been curtailed from an initial $2 billion to $900 million, while FORA, which previously provided $1 billion in taxpayer-backed reinsurance, has been completely disbanded. Although not every primary insurer in Florida utilized these state-funded options, their presence offered a vital safety net. The current market conditions, characterized by an increased supply of reinsurance and insurance-linked securities (ILS) capital, alongside more competitive pricing for catastrophe bond coverage, appear to underpin this move. However, the elimination of approximately $2.1 billion in state-backed reinsurance capacity means that Florida's carriers will need to seek expanded protection from conventional reinsurance markets or through ILS investments, potentially boosting demand for risk capital in the upcoming year.
From a market perspective, this legislative adjustment underscores a strategic pivot towards market-driven solutions. While the immediate implications suggest a more robust private market for Florida's insurance needs, it also highlights potential vulnerabilities should the state face a resurgence of challenges or significant hurricane activity. The reliance on private capital may offer greater efficiency and innovation, yet it also raises questions about the accessibility and affordability of coverage during periods of heightened risk. This dynamic shift demands continuous monitoring to ensure the enduring resilience and stability of Florida's insurance sector.